Refinancing and mortgage switching services in Switzerland
Refinancing your mortgage in Switzerland can be one of the most effective ways to reduce long-term housing costs, improve financial flexibility, and secure better lending conditions. With interest rates changing frequently and mortgage products varying greatly between Swiss banks, insurance companies, and lenders, many homeowners are unaware of the potential savings available by switching providers or renegotiating the terms of their existing mortgage. A professional mortgage broker can help you navigate this complex market and make the best financial decision based on your unique situation (refinancing and mortgage switching services in Switzerland).
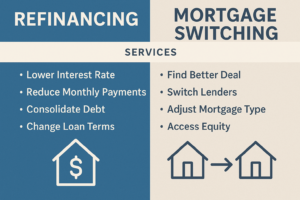
Mortgage refinancing typically involves replacing your current loan with a new mortgage that offers better conditions. This can include securing a lower interest rate, switching from a fixed-rate to a variable-rate mortgage (or vice versa), or extending or shortening the mortgage term. Refinancing is especially attractive when market rates drop, but it can also be advantageous when your financial situation has improved and you now qualify for more favorable terms.
Mortgage switching, on the other hand, involves transferring your mortgage from one lender to another—often to benefit from lower interest rates, improved service, or more flexible amortization options. In Switzerland, different lenders may offer significantly different conditions, so a structured comparison is essential. Even a small reduction in interest rate can lead to considerable savings over time.
A key part of successful refinancing or switching is understanding the potential costs and penalties, particularly if your current mortgage is fixed-term. Some lenders charge early repayment fees (Vorfälligkeitsentschädigung), which need to be carefully calculated to determine whether switching still results in overall savings. A mortgage broker can analyze these costs and compare them against the potential long-term benefits to determine if refinancing makes financial sense.
Working with an experienced Swiss mortgage broker provides several advantages. Brokers have access to a wide network of banks, insurance companies, and alternative lenders, allowing them to negotiate better rates and terms on your behalf. They also provide a clear, unbiased comparison of your options, ensuring that you understand the total cost of ownership and long-term financial impact.
In addition to securing better conditions, refinancing can also help homeowners consolidate debt, adjust their amortization schedule, or transition to a mortgage structure that better aligns with their financial goals. For example, some clients may choose to reduce their amortization to free up liquidity, while others prefer to accelerate repayment to reduce overall debt.
Ultimately, refinancing or switching your mortgage is not just about securing the lowest rate—it’s about optimizing your long-term financial strategy. With the right guidance, Swiss homeowners can make informed decisions that lead to significant savings and improved financial stability.