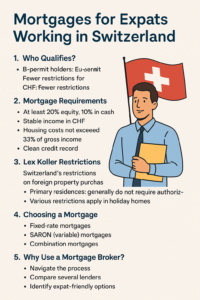
Mortgages for expats in Switzerland
Buying property in Switzerland as an expat can be a highly rewarding long-term investment, but the mortgage process is often more complex than it is for Swiss citizens or permanent residents. Each lender applies its own specific rules depending on nationality, residence status, income source, taxation, and long-term plans in the country. Understanding how Swiss mortgage rules apply to foreign nationals is the first step in securing the right financing solution and avoiding unnecessary delays or rejections (mortgages for expats in Switzerland).
1. Who Qualifies as an Expat Homebuyer in Switzerland?
Switzerland welcomes a diverse international workforce, and many expats are eligible for mortgages. Generally, you qualify if you hold a B-permit (residence permit) or a C-permit (permanent residence). EU/EFTA nationals with a B-permit enjoy easier access, while non-EU citizens may face additional restrictions depending on the canton and property type. If you work in Switzerland but live across the border (a “Grenzgänger”), some banks will still offer mortgages, but conditions may be stricter.
2. Mortgage Requirements for Expats
Swiss lenders rely on conservative affordability rules. Most require:
- At least 20% equity, with a minimum of 10% in cash savings
- Stable income generated in Switzerland (or a recognised foreign employer)
- Housing costs not exceeding 33% of gross income
- Clean credit record (from Switzerland and sometimes from your home country)
Income paid in foreign currency may reduce your borrowing capacity due to exchange-rate risk. Proof of long-term employment—such as a permanent contract or multi-year assignment—often strengthens your application significantly.
3. Restrictions Under Lex Koller
The Swiss law known as Lex Koller regulates property purchases by foreign nationals. Most expats with a B-permit are allowed to purchase a primary residence, but restrictions apply to holiday homes and investment property unless specific exemptions are granted. C-permit holders are treated similarly to Swiss citizens for most purposes.
4. Choosing the Right Mortgage as an Expat
Expats can access the same mortgage products as Swiss nationals, including:
- Fixed-rate mortgages
- SARON (variable) mortgages
- Combination mortgages
However, some banks offer customised options for expats, especially for those paid in foreign currency or relocating frequently. A mortgage broker can help compare dozens of lenders and identify which ones specialise in international clients.
5. Why Expats Benefit From Using a Mortgage Broker
Mortgage brokers are especially valuable for expats because they:
- Compare offers across Swiss banks, insurers, and digital lenders
- Identify expat-friendly institutions
- Help navigate Lex Koller rules and cantonal regulations
- Assist with document preparation and income verification
- Negotiate better interest rates and conditions
This professional guidance often saves both time and money, ensuring your application is structured correctly from the start.