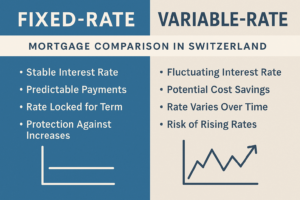
Fixed vs. Variable Mortgage Comparison Switzerland
Choosing between a fixed or variable mortgage is one of the most important decisions for homebuyers in Switzerland. Both options offer unique advantages, and the right choice depends on your financial situation, risk tolerance, and long-term goals. This guide provides a clear and neutral comparison to help you make an informed decision when selecting your ideal mortgage structure (fixed vs. Variable Mortgage Comparison in Switzerland).
A fixed-rate mortgage offers stability and predictability. With this option, your interest rate remains unchanged for the entire mortgage term, which can range from one year to ten years or more. Because the rate is locked in, you always know exactly how much you’ll pay each month. This makes fixed mortgages particularly appealing to buyers who prefer long-term financial planning or want protection against potential interest rate hikes. Fixed mortgages are especially popular in Switzerland during times of rising or uncertain market conditions.
A variable-rate mortgage, on the other hand, is linked to short-term market interest rates such as SARON. This means your mortgage rate can increase or decrease over time, giving you more flexibility and the potential to benefit from lower interest rates. Variable mortgages typically do not require a fixed term, allowing borrowers to switch to another mortgage model more easily. This option tends to be attractive when market rates are stable or decreasing, or when a borrower expects short-term financing changes such as selling a property or refinancing.
The main difference between fixed and variable mortgages is the level of risk and predictability. Fixed mortgages reduce risk by locking in a long-term rate, while variable mortgages introduce fluidity and the possibility of savings—at the cost of potential rate increases. When choosing between the two, it’s important to consider your financial stability. If you prefer consistent monthly payments without surprises, a fixed rate may be the better fit. If you are comfortable with market fluctuations and want the possibility of lower payments, a variable mortgage might suit you more.
Swiss lenders also offer hybrid solutions, combining a portion of the mortgage at a fixed rate and another at a variable rate. This can help balance stability with flexibility. Many borrowers choose this blended approach to benefit from rate reductions while still protecting part of their financing against market volatility.
Comparing fixed and variable mortgages is not simply about choosing the cheaper option. It requires evaluating your personal risk profile, real estate plans, and long-term financial expectations. Working with a professional mortgage broker can help you analyze the market, compare offers from multiple Swiss banks, and find the most suitable structure for your situation.
Ultimately, the right mortgage model is the one that aligns with your comfort level and financial objectives. A clear understanding of both options ensures you make a confident and informed decision in the Swiss mortgage market.