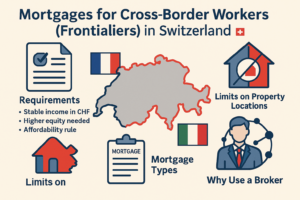
Mortgages for cross-border workers Switzerland
Buying property in Switzerland or in nearby border regions is increasingly attractive for cross-border workers, also known as frontaliers. These individuals typically live in France, Germany, or Italy and commute daily to work in Switzerland. While frontaliers enjoy Swiss salaries, getting a mortgage can come with unique requirements, limitations, and opportunities. Understanding how Swiss lenders evaluate foreign-resident borrowers is essential for successfully securing financing (mortgages for cross-border workers Switzerland).
1. Who Qualifies as a Frontalier?
A frontalier is someone who:
- Lives in a neighboring country (France, Germany, Italy, Austria)
- Works in Switzerland with a G-permit
- Commutes regularly across the border
Frontaliers can apply for Swiss mortgages, but conditions vary significantly depending on the lender, the location of the property, and the borrower’s home country.
2. Mortgage Eligibility Requirements
Lenders use stricter criteria for cross-border applicants than for Swiss residents. Typical requirements include:
- Stable income in CHF or employment in Switzerland (minimum 6–12 months).
- Higher equity requirements: Minimum 20% down payment, but some lenders ask for 25–30%.
- At least 10% cash contribution (not from pension funds).
- Clean credit history in both Switzerland and the country of residence.
- Affordability rule: Total housing costs must not exceed 33% of gross income.
Some lenders also require that frontaliers open a Swiss bank account and maintain salary transfers there.
3. Limits on Where Frontaliers Can Buy
Frontaliers generally have two main options:
A. Buying Property in Switzerland
Many lenders allow this, but rules vary:
- Primary residences are usually allowed.
- Secondary homes or investment properties are more restricted.
- Certain cantons apply additional limitations under Lex Koller regulations.
B. Buying Property in Neighboring Countries with a Swiss Mortgage
Some Swiss banks (especially in border regions) provide mortgages for properties located in:
- France (especially Haute-Savoie, Pays de Gex, Alsace)
- Germany (Baden-Württemberg)
- Italy (Lombardy)
However, the valuation and legal processes may differ, and not all lenders offer foreign-property mortgages.
4. Mortgage Types Available
Frontaliers can typically access the same products offered to Swiss residents, including:
- Fixed-rate mortgages
- SARON (variable-rate) mortgages
- Combination mortgages
Interest rates may sometimes be slightly higher for frontaliers due to additional risk factors.
5. Why Frontaliers Benefit from a Mortgage Broker
Working with a broker is extremely valuable for cross-border buyers because:
- Not all lenders accept frontaliers — a broker identifies the ones who do.
- Brokers compare rates across multiple banks and insurance companies.
- They understand cross-border taxation, currency risk, and legal requirements.
- They help navigate complex paperwork in both countries.
This guidance often results in lower interest rates, simpler processing, and improved approval chances.