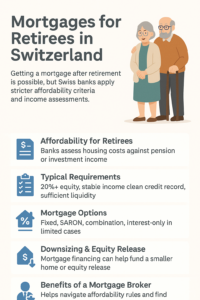
Mortgages for retirees in Switzerland
As Switzerland’s population ages, more retirees are exploring ways to finance property purchases, downsize, renovate, or release equity from their homes. While obtaining a mortgage after retirement is certainly possible, Swiss banks apply stricter criteria compared to borrowers in full-time employment. Understanding how lenders assess retirement income, affordability, and risk is essential for securing the right mortgage solution later in life (mortgages for retirees in Switzerland).
1. Can Retirees Get a Mortgage in Switzerland?
Yes — retirees can access mortgages, both for primary residences and second homes. However, the approval process can be more challenging because lenders evaluate long-term affordability based solely on pension income, investment income, or other stable sources. Banks aim to ensure borrowers can comfortably maintain payments for the next 15–20 years.
2. How Affordability Works for Retirees
Swiss affordability rules remain the same regardless of age. Total housing costs (mortgage interest, amortization, and maintenance) must not exceed one-third of gross income. However, retirees often have reduced income levels, so lenders scrutinize affordability more strictly.
Banks may accept the following as income:
- AHV/AVS pension payments
- Occupational pension income (Pillar 2)
- Private pensions and annuities (Pillar 3a/3b)
- Investment income, rental income, or dividends
- Proof of substantial savings or wealth to cover costs
Borrowers with significant assets often benefit from wealth-based affordability calculations, making mortgages easier to obtain.
3. Typical Mortgage Requirements for Retirees
Most Swiss lenders require:
- At least 20% equity (often more for retirees)
- Verified, stable pension income
- Clean credit record
- Proof of sufficient liquidity for long-term sustainability
Some banks may request larger down payments (25–40%) to reduce lending risk, especially when pension income is modest.
4. Mortgage Options Available to Retirees
Retirees can choose among:
- Fixed-rate mortgages – predictable and stable payments
- SARON mortgages – interest rate varies with the Swiss money market
- Combination mortgages – split between fixed and SARON
- Interest-only mortgages – available only in limited cases for those who can demonstrate strong asset reserves
Refinancing is also available, allowing retirees to benefit from lower rates or better terms.
5. Downsizing, Renovation & Equity Release
Many retirees use mortgages to:
- Purchase a smaller, more manageable home
- Renovate their existing property for accessibility
- Unlock equity to support retirement expenses or family members
Swiss banks also offer reverse-style mortgage solutions in some cases, though these are less common and vary by lender.
6. Why Work With a Mortgage Broker?
A broker offers valuable support by:
- Comparing lenders who are retiree-friendly
- Identifying banks that allow wealth-based affordability
- Securing more flexible terms
- Reducing administrative burden
- Negotiating competitive interest rates
Given the complexity of retiree mortgages, professional guidance can significantly improve approval chances and financial outcomes.